

Canadian renters have discovered a powerful financial strategy: using credit cards to pay monthly rent. This approach transforms your largest recurring expense into an opportunity to earn substantial rewards and build credit by paying rent. With housing costs consuming significant portions of household budgets in major cities, maximizing returns on these unavoidable payments makes financial sense.
Paying rent with the right credit card can earn substantial cashback - Neobanc adds 1% cashback on rent payments on top of your card's own rewards, making it one of the most rewarding options available to Canadian tenants. However, most landlords don't accept credit cards directly. This gap creates the need for third-party payment platforms that bridge traditional landlord preferences with modern payment methods.
This guide covers the best credit cards for rent payments, explains how payment platforms work, and reveals strategies to maximize rewards while earning cashback on rent. Whether you're looking to accumulate travel points, earn cashback, or strengthen your credit score for renting, the right card and platform combination can transform your rent from a pure expense into a wealth-building tool.
Understanding the mechanics of credit card rent payments helps you make informed decisions about which cards and platforms to use. The process involves a few straightforward steps that connect your credit card rewards to your monthly housing payments.
Landlords typically don't accept credit cards directly because of the processing fees involved. Third-party platforms solve this problem by acting as intermediaries. You pay the platform with your credit card, and it pays your landlord directly, so the landlord receives what looks like a standard payment.
These rent payment platforms have processed billions of dollars in rent. TenantPay, for example, says it has processed billions of dollars for millions of renters since 2006.
Payment platforms charge a processing fee on card payments, typically between 1.5% and 2.75% of your rent, and 1.75% is the most common rate, according to Milesopedia. This means choosing high-reward cards becomes essential to offset costs and generate positive returns. The math works in your favor when your card's rewards exceed the platform's fees.
It's worth noting what you can and cannot pay with credit cards. Through a payment platform, most bills can go on a card, including rent, utilities, property taxes and subscriptions. Mortgages vary by platform: Chexy, for example, accepts mortgages only by debit, as Milesopedia notes.
Beyond rewards, paying rent with a credit card offers credit-building advantages. Regular on-time payments demonstrate responsible credit usage, which can improve your credit score over time. Some platforms also offer rent reporting to credit bureaus, adding another layer of credit-building benefit to your monthly payments.
Selecting the right credit card determines whether your rent payments generate meaningful returns or barely break even after platform fees. The following cards stand out for their rewards on recurring bill payments, making them ideal choices for Canadian renters seeking to maximize their monthly housing expenses.
The Scotia Momentum Visa Infinite+ Card used to lead the pack for rent payments. Since October 22, 2026, Scotiabank's cash back terms no longer count rent and tax payments as recurring bills, so rent earns the card's 1% base rate. Here is what that means for renters:
The card still works well for utilities and subscriptions billed directly to it, but for rent it now earns less than platforms charge in fees.

The TD Cash Back Visa Infinite Card provides another solid option for rent payments. It earns 3% cash back on recurring bill payments, groceries, gas, EV charging and transit, on up to $15,000 of spending a year in each category, then 1%, and costs $139 a year, according to TD. TD only pays the 3% when the Visa network classifies a charge as a pre-authorized recurring payment, so check the category on your first statement, as Milesopedia advises.
For renters spending $1,600 monthly on rent and bills, this card generates approximately $13 in cashback per month, translating to $156 yearly after a 1.75% platform fee. With the Scotia card now earning 1% on rent, this is the strongest big-bank cash back option for rent in this guide.

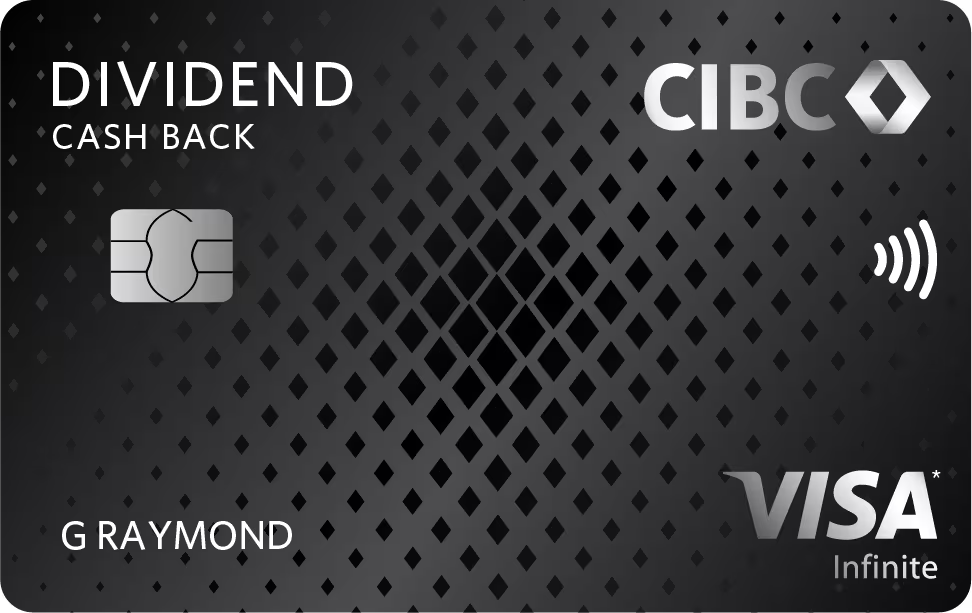
The CIBC Dividend Visa Infinite takes a different approach to rewards. CIBC pays 4% cash back on groceries, gas and EV charging, 2% on transportation, dining and recurring payments, and 1% on everything else, for a $120 annual fee. The 4% and 2% rates stop at $20,000 of eligible spending a year, according to CIBC's benefits guide.
The 2% rate on recurring payments means rent payments earn $4 monthly or $48 annually after a 1.75% platform fee, if CIBC codes the payment as a recurring bill. This card shines for renters who want to maximize grocery spending while still earning something on rent. The combined rewards across categories can make it worthwhile despite the lower rent-specific returns.
The Neo World Mastercard has no annual fee. On its Gas & Grocery plan, it earns 2% on gas, EV charging, groceries and recurring payments, but recurring payments are capped at $500 a month and earn 0.5% after that, according to Neo. Neo counts utilities, telecom, subscriptions, insurance and gym memberships as recurring payments, so don't count on the 2% for rent. The older perk that doubled the rate to 4% with $10,000 in a Neo Everyday account ended in October 2025, Milesopedia reports.
Its pricier sibling, the Neo World Elite Mastercard ($149 a year), pays 4% on recurring payments under the same definition, again only on the first $500 a month. Either card works better for everyday groceries, gas and bills than for rent, though a no-fee card can still help renters looking to build credit in Canada.
Best Credit Cards for Rent Payments Comparison
| Card Name | Cashback Rate | Annual Cap | Monthly Earnings on $1600 | Net Annual After Fees |
|---|---|---|---|---|
| Scotia Momentum Visa Infinite+ | 1% | No cap | $16 | -$144 |
| TD Cash Back Visa Infinite | 3% | $15,000/year | $48 | $156 |
 Amex Cobalt Card | 1x points | No cap | $16 | -$144 |
| CIBC Dividend Visa Infinite | 2% | $20,000/year | $32 | $48 |
Net figures assume $1,600 of rent a month and a 1.75% platform fee, before each card's own annual fee.
When evaluating these cards, calculate your true annual value by subtracting both the card's annual fee and platform fees from your total rewards earned. A card with a $120 annual fee generating $432 in cashback still nets $312 - far superior to a no-fee card earning $156.
For renters with limited credit history, starting with a no credit check option and graduating to premium rewards cards creates a smart progression. Ratehub notes that most Canadians should wait at least 3 to 6 months between credit card applications, as each application triggers a hard inquiry that can temporarily lower credit scores.
For renters who prefer airline miles and hotel points over cashback, several travel cards transform monthly housing payments into future adventures. These cards particularly reward high spenders who can offset platform fees with valuable point redemptions. Both cards below are American Express cards, and Neobanc takes Visa and Mastercard only, so you would need a payment platform that takes Amex.
The American Express Aeroplan Reserve Card stands as the premium choice for travel-focused renters. Its earn rates, as listed by Air Canada, are:
With $1,600 monthly in rent and bills, cardholders earn 2,000 points monthly and 24,000 points yearly. This equates to approximately $168 in yearly net rent rewards after platform fees, assuming standard point valuations, before the card's $599 annual fee, which rises to $799 for fees charged from January 12, 2027.
The American Express Cobalt Card won Best Overall Rewards Credit Card in Ratehub's credit card awards. It earns 5 points per dollar on eats and drinks (on up to $2,500 a month), 3 on streaming and 2 on gas, transit and rideshare, but only 1 point per dollar on rent, so its value for renters comes from its versatile redemption options rather than from rent itself.
The card's monthly fee of $15.99 (about $192 a year) rather than an upfront annual fee appeals to those who want to try premium cards without long-term commitment. For renters exploring their first credit cards, the Cobalt provides an accessible entry point into premium rewards.
Travel cards require strategic thinking to extract maximum value from rent payments. Consider these approaches:
Renters focused on rent to own opportunities might prefer cashback cards that contribute to down payment savings, while those committed to long-term renting can benefit from accumulating travel points through their housing expenses.
Not every renter wants to pay annual fees, even for higher rewards. Several no-fee cards still earn something on rent without requiring annual financial commitments, though their rates rarely beat platform fees. These options work well for easy approval situations and renters building their credit foundations.
The BMO CashBack Mastercard delivers practical value without fees. According to Milesopedia, it provides:
Because the 1% rate stops after $500 of recurring bills per statement, $1,600 of rent earns about $10.50 a month before platform fees, and only if BMO codes the payment as a recurring bill. That is less than a typical platform fee, so this card makes more sense for groceries than for rent. The grocery bonus adds value for renters managing tight budgets across all spending categories.

The no-fee Scotiabank American Express Card earns 3 Scene+ points per dollar at Sobeys, Safeway, FreshCo and Foodland, 2 points on dining, other groceries, entertainment, gas, transit and streaming, and 1 point on everything else, including rent, according to Scotiabank. Scene+ points are worth about one cent each, so rent earns roughly 1%.
This card particularly suits grocery shoppers and moviegoers who can redeem points at Cineplex locations. Like the travel cards above, it needs a payment platform that takes American Express.

Renters with limited or damaged credit histories can still build credit through secured cards. The Secured Neo Mastercard, which Ratehub named the best card for building credit in its credit card awards, requires a minimum security deposit of just $50. Its cash back comes mainly from Neo's partner offers rather than a flat rate on all spending.
While secured cards offer lower rewards, they serve a crucial purpose: establishing or rebuilding credit. Renters can use these cards strategically to improve their credit scores for future apartment applications.
For those seeking guaranteed approval options, secured cards provide a reliable path forward. The credit building journey often starts with these foundational products before graduating to premium rewards cards.
Your choice of rent payment platform affects both your costs and your overall experience. Different platforms offer varying fee structures, landlord payment methods, and additional features that can enhance or diminish your rewards-earning strategy.
When evaluating platforms, consider these factors:
Some platforms offer rent reporting services that send your payment history to credit bureaus. This dual benefit - earning rewards while building credit - maximizes the value of every rent payment. Understanding how rent affects your credit score helps you make informed platform decisions.
To break even, your card has to earn at least as much as the platform charges. If a platform charges 1.75% and your card earns 3%, you net 1.25% on every rent payment - pure profit on an expense you'd pay regardless.
Neobanc improves every row in the table above by adding its own cashback on top of your card's rewards. That stacking makes rent payments genuinely profitable rather than merely rewards-neutral.
Late rent payments damage your relationship with landlords and potentially your tenancy. Choose platforms with proven track records and clear policies on payment timing. Reading reviews from other Canadian renters provides insight into real-world reliability.
Consider having a backup payment method ready in case of platform issues. The convenience of credit card payments shouldn't come at the cost of payment reliability when your housing depends on it.
Earning rewards on rent payments represents just one element of a comprehensive financial strategy. Combining the right card, platform, and spending habits amplifies your returns beyond simple rent payments.
Many Canadian renters overlook opportunities to stack rewards. Consider these strategies:
The combination of card rewards, platform bonuses, and credit building creates multiple value streams from a single monthly payment.
Credit card statement cycles affect your credit utilization ratio, which impacts your credit score. Paying rent early in your billing cycle gives you time to pay down the balance before statement close, keeping utilization low while still earning rewards.
For renters working toward mortgage readiness, maintaining low credit utilization while demonstrating consistent payment history strengthens mortgage applications. The discipline of strategic rent payments prepares you for eventual homeownership decisions.
Credit card rent payments can backfire if managed poorly. Avoid these mistakes:
Most Canadian credit cards add a 2.5% foreign transaction fee to purchases made abroad, though a few no-fee cards waive it, as NerdWallet Canada notes. While this doesn't affect domestic rent payments, international travelers should consider this factor when selecting their primary rewards card.
The best credit card to pay rent in Canada depends on your spending patterns, rewards preferences, and credit situation. The TD Cash Back Visa Infinite is now the top big-bank choice in this guide for pure cashback on rent, as long as TD codes the payment as a recurring bill, since the Scotia Momentum Visa Infinite+ dropped to 1% on rent on October 22, 2026. The American Express Aeroplan Reserve Card leads for travel rewards seekers who use a platform that takes Amex. Budget-conscious renters can still earn a little with no-fee options like the BMO CashBack Mastercard, though usually less than the platform fee.
Remember these key points when setting up your rent rewards strategy:
Canadian renters have a genuine opportunity to transform their largest monthly expense into a wealth-building tool. Whether you're saving for a down payment through cashback or accumulating points for dream vacations, the right credit card and platform combination puts your rent to work for your financial goals.
Since October 22, 2026, the Scotia Momentum Visa Infinite+ earns only 1% on rent, so it is no longer the top pick. For straight cashback, the TD Cash Back Visa Infinite now leads the big-bank cards in this guide: 3% on recurring bill payments on up to $15,000 a year, then 1%, as long as TD codes your rent payment as a recurring bill. On $2,000 monthly rent, that is about $540 a year in card cashback, and paying through Neobanc adds its own cashback on top, before the platform's card fee.
Yes. A card that earns 3% on rent earns $60 a month on $2,000 rent, and paying through Neobanc adds its own cashback on top of that, before the platform's card processing fee.
Most Canadian rent payment platforms charge 1.75% for credit card payments, about $35 a month on $2,000 rent, and fees run from about 1.5% to 2.75%. Neobanc adds its own cashback on top of your card's rewards. The fee is only worthwhile if your card earns more than the fee costs, which is why a card that earns 3% on rent matters far more than a 1% everyday card.
Not if you manage it carefully. Charging $2,000 of rent monthly raises your credit utilization, which accounts for 30% of your score. Keep your balance under 30% of your credit limit and pay the statement in full each month. Done this way, paying rent on a card can actually help your score because payment history makes up 35% of your credit profile. Carrying a balance or maxing out your card, however, will hurt it.
Very rarely. Most Canadian landlords avoid credit cards because of processing fees and accounting complexity, preferring cheques, pre-authorized debit or other bank payments. To earn rewards on rent, renters use a third-party platform that charges their card and pays the landlord directly. The landlord receives a normal payment and never knows a card was used, so you keep your rewards without any landlord involvement.
It depends on your card. A card that earns 3% on rent earns $60 a month on $2,000 rent, and a platform that adds its own cashback raises that further, before the card fee. With a 1% card, the processing fee eats most or all of the gain. It is worth it when your card earns well above the fee, and especially when a platform adds its own cashback on top. Always pay the balance in full to avoid interest.
For straight cashback, the TD Cash Back Visa Infinite leads the big-bank cards in this guide at 3% on recurring bill payments, on up to $15,000 a year; the Scotia Momentum Visa Infinite+ now earns 1% on rent. For travel points, the American Express Aeroplan Reserve earns 1.25 Aeroplan points per dollar on rent through platforms that take Amex. The best choice depends on whether you value cash or travel rewards. For most renters, a high-rate cashback card paired with a stacking platform delivers the clearest, highest net return on every rent payment.